Updated 4 September 2026
Many investors were persuaded to transfer established pension benefits into self-invested personal pensions (SIPPs) before placing substantial sums into tree plantations in Costa Rica. Although Ethical Forestry itself was unregulated, affected investors may still have potential claims against regulated financial advisers, pension firms or other businesses involved in arranging their investments.
If you invested in Ethical Forestry personally or through a pension, you may still be able to claim compensation, even though the investment itself was unregulated.
Talk to Claim My Loss for a free, no obligation initial assessment. No win, no fee if you decide to go ahead.
What was the Ethical Forestry investment?
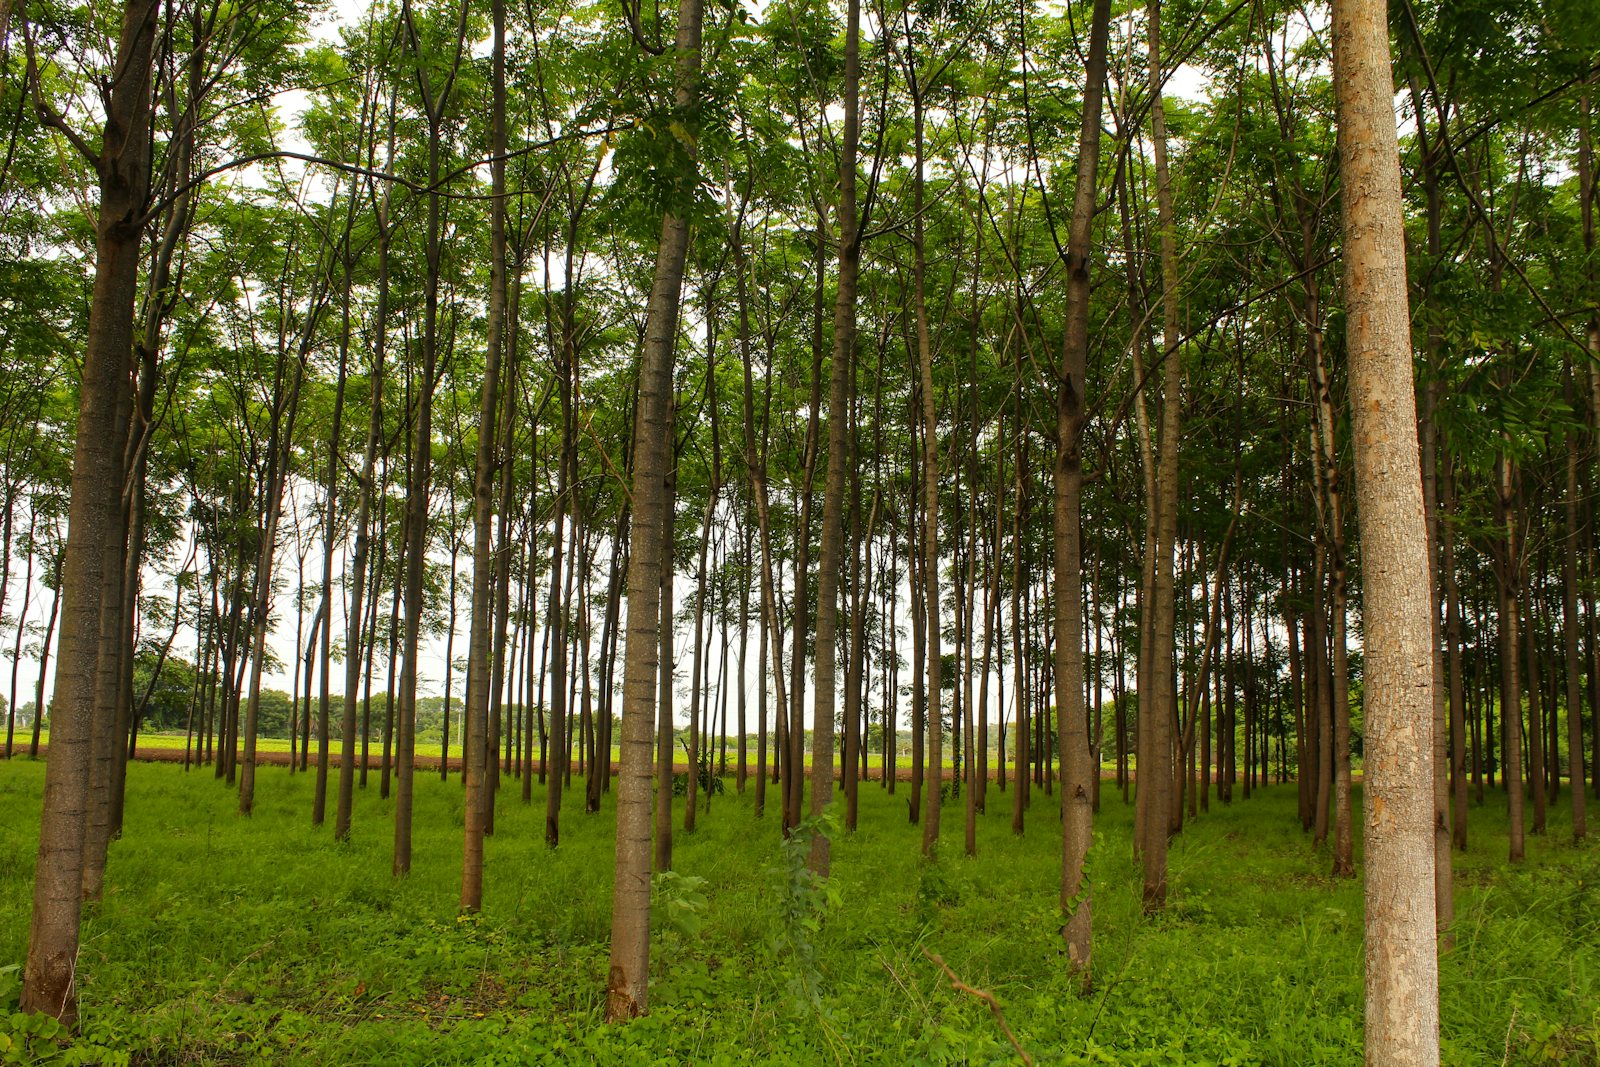
Ethical Forestry Limited promoted investments in Melina tree plantations in Costa Rica. Investors were told that their money would be used to plant and maintain trees, which would subsequently be harvested to generate returns. The investment was presented as an opportunity to combine potentially attractive financial returns with the environmental benefits of forestry. Products included different versions of the Melina tree investment, with returns supposedly generated through thinning and harvesting the trees over several years. However, the Serious Fraud Office’s investigation found that although some trees were planted, no money was set aside to maintain the trees or carry out a commercial harvest. As a result, the plantations could never generate the returns investors had been promised. Ethical Forestry entered creditors’ voluntary liquidation in December 2015.
How were investors approached?
According to the Serious Fraud Office, Ethical Forestry operated a call centre in Bournemouth whose employees cold-called members of the public and offered pension reviews. The callers sometimes used alternative company names, including:
- Richmond Solutions;
- The Pension Report Service.
Consumers were not always told that the people contacting them were working for Ethical Forestry. Investors were then encouraged to withdraw or transfer money from legitimate pension arrangements and invest it in the Costa Rican forestry scheme. In many cases, the transaction involved several different businesses. An unregulated introducer might have made the initial contact, while a regulated financial adviser arranged or recommended the pension transfer and a SIPP operator accepted the Ethical Forestry investment. This wider chain of involvement can be extremely important when assessing whether an investor has a viable claim.
What happened to the investors’ money?
The SFO found that investor money was used to fund the directors’ lifestyles. This included expensive properties, luxury holidays and high-performance cars. The investigation also found that £2.77 million of investors’ money was diverted to administer a tax-avoidance arrangement for the directors’ benefit. Matthew Pickard, Stephen Greenaway and Paul Laver pleaded guilty to fraudulent trading in January 2026. On 3 September 2026, Southwark Crown Court imposed the following sentences:
- Matthew Pickard, six years’ imprisonment;
- Stephen Greenaway, five years and three months’ imprisonment;
- Paul Laver, four years and six months’ imprisonment.
All three were also disqualified from acting as company directors for ten years. The SFO’s criminal investigation has now concluded, although its proceedings to identify and recover the defendants’ assets are continuing.
Was Ethical Forestry regulated by the FCA?
The Ethical Forestry investment was an unregulated overseas forestry investment. It did not benefit from the protections that ordinarily apply to conventional FCA-regulated pension funds and investments. However, the fact that the underlying investment was unregulated does not necessarily mean an investor has no right to compensation. A claim may arise where an FCA-authorised financial adviser recommended or arranged an unsuitable pension transfer or investment. There may also be grounds to investigate a SIPP operator that accepted the business, depending upon the dates, documentation and particular circumstances. The involvement of businesses such as Avacade is especially significant. In 2020, the High Court found that Avacade Limited and Alexandra Associates (UK) Limited had unlawfully advised on and arranged investments without FCA authorisation. More than 2,000 consumers transferred approximately £91.8 million into SIPPs, with around £68 million invested in products promoted by Avacade. The FCA obtained a restitution order of approximately £10.7 million against Avacade, Alexandra Associates and their directors. The FCA subsequently secured bankruptcy orders against Avacade directors after the restitution order was not satisfied.
Have Ethical Forestry complaints previously succeeded?
Yes. Published Financial Ombudsman Service decisions demonstrate that complaints involving Ethical Forestry can succeed where a regulated business was responsible for arranging or advising upon the transaction. In one published decision, the Ombudsman upheld a complaint against Pi Financial Ltd concerning a consumer who transferred approximately £36,800 from existing pensions into a SIPP and invested nearly £36,000 in Ethical Forestry. The firm argued that it had acted on an execution-only basis and had not provided investment advice. The Ombudsman nevertheless concluded that the consumer was not a genuine execution-only investor and that the firm had failed to act in her best interests. The Ombudsman described Ethical Forestry as a high-risk, unregulated and illiquid overseas investment. It found that the firm should either have refused to proceed on an execution-only basis or established whether the transaction was appropriate for the consumer. Compensation was directed at placing the investor as closely as possible into the position she would have occupied had her original pensions not been transferred. Every case depends on its own facts, but the decision demonstrates that signing an “execution-only” form does not always prevent a successful complaint.
Who might an Ethical Forestry claim be made against?
A potential claim will normally require an investigation into every business involved in the transaction. This may include:
- the financial adviser who recommended or arranged the pension transfer;
- the adviser’s appointed representative or principal firm;
- the SIPP operator that accepted the investment, for example Liberty SIPP or GPC SIPP Ltd;
- an authorised firm that approved or facilitated the transaction;
- any other regulated business whose actions caused or contributed to the loss.
Important evidence may include pension transfer forms, suitability reports, SIPP applications, investment certificates, illustrations, risk questionnaires, letters of authority and communications with introducers or advisers. The identity of the firm that received commission or other payments can also be relevant.
Could the Financial Services Compensation Scheme help?
The Financial Services Compensation Scheme may be able to pay compensation where an FCA-authorised firm is no longer trading and cannot meet a valid claim itself. The FSCS does not ordinarily compensate investors merely because an unregulated investment has failed. It will need to establish a protected claim against a regulated firm, for example for unsuitable pension or investment advice. Where the responsible regulated business remains trading, the complaint would normally be made to that firm first and could potentially be referred to the Financial Ombudsman Service if it is rejected or not resolved within the applicable period. The SFO has expressly confirmed that Ethical Forestry investors who meet the relevant criteria may be entitled to claim through the FSCS.
What about compensation through the criminal proceedings?
The SFO is continuing proceeds-of-crime work to recover assets from the convicted directors. It has warned investors that any court compensation order is unlikely to recover the whole of their investment and that payments may be made gradually as assets are recovered. The published deadline for completing the SFO’s victim questionnaire was 3 September 2026. Anyone who missed that deadline should contact the SFO promptly at ethical@sfo.gov.uk to ask whether their information can still be included. Investors should not assume that possible recovery through the criminal proceedings prevents them from investigating other compensation routes. However, compensation already received would normally need to be taken into account to avoid recovering the same loss twice.
What should Ethical Forestry investors do now?
Investors should locate as much of the following information as possible:
- the name of the pension or SIPP provider;
- the name of the financial adviser and advisory firm;
- details of the person or business that first contacted them;
- the date and amount of the investment;
- Ethical Forestry certificates or contracts;
- pension transfer and SIPP application documents;
- suitability or recommendation reports;
- correspondence referring to an execution-only service;
- records of commission, fees or introducer payments;
- any previous complaints or compensation received.
Financial complaints and compensation claims are subject to time limits. Investors should therefore seek an assessment without unnecessary delay, even if they only recently discovered that the advice or arrangements surrounding their pension may have been unsuitable.
How Claim My Loss can help
Claim My Loss can investigate the complete chain of events surrounding an Ethical Forestry investment. We can examine how the investor was introduced, whether pension advice was provided, which regulated firms participated and whether the transaction should have proceeded. Where appropriate, we can consider potential routes through the financial adviser, the Financial Ombudsman Service or the Financial Services Compensation Scheme. The collapse of Ethical Forestry does not automatically mean that the opportunity to recover compensation has been lost. The decisive issue may be what the regulated firms involved knew, what they recommended and whether they acted in the investor’s best interests. If you invested in Ethical Forestry personally or through a pension, contact Claim My Loss for an initial assessment of your circumstances. Each claim is assessed on its individual facts. Compensation is not guaranteed, and applicable eligibility requirements and time limits will apply.
Sources: Serious Fraud Office: Ethical Forestry directors sentenced; SFO Ethical Forestry case information and investor guidance; FCA High Court proceedings against Avacade; FCA update on the Avacade directors; Financial Ombudsman decision DRN7666898.